Category

Insurance news

Risk presentation — not price haggling — drives renewal outcomes, Everywhen says

Businesses approaching renewal should stop asking simply how to bring the price down and start asking how to become a better risk, according to Everywhen.

With UK businesses facing continued pressure from employment costs, business rates, energy bills and wider operating expenses, the insurer and risk advisory group says reducing premiums understandably becomes a priority, but warns that an excessive focus on price can cause businesses to overlook the single biggest factor shaping their insurance outcome: how their risk is understood, managed and presented to insurers in the first place.

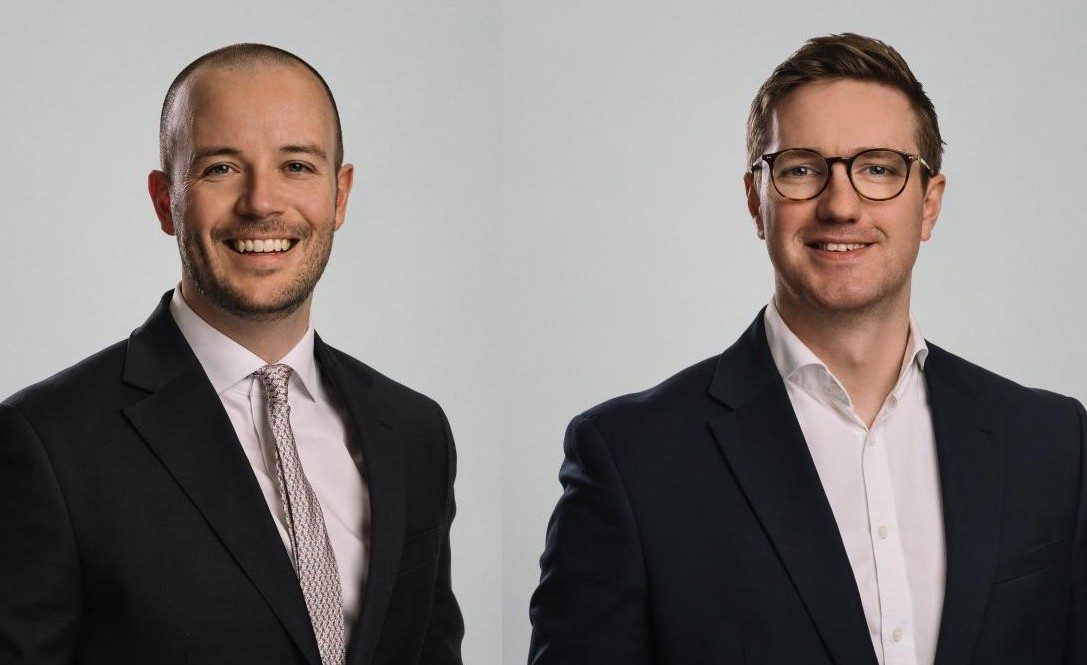
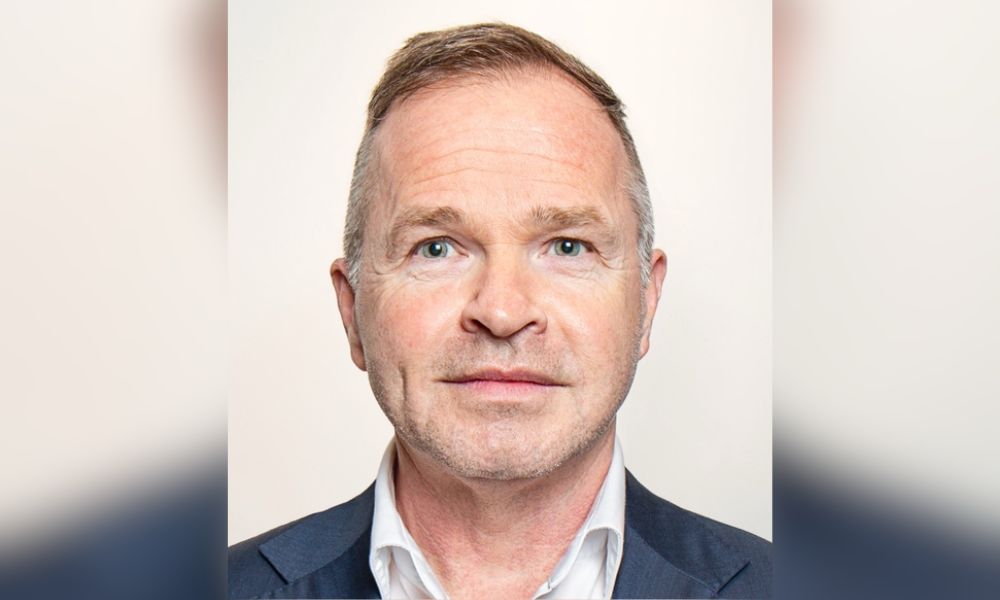
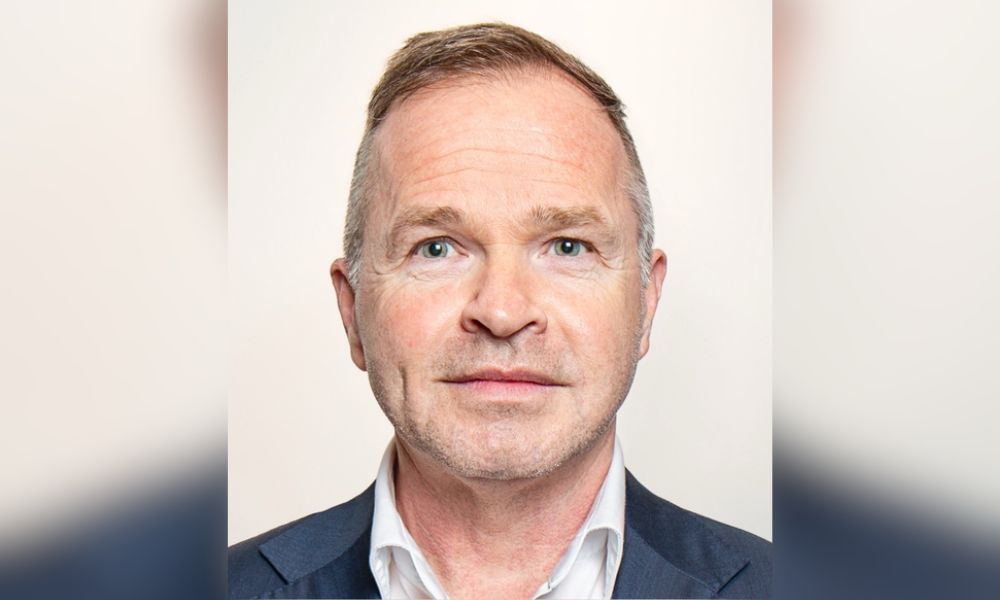
Chris Brady (pictured), chief executive of corporate, international and risk advisory services at Everywhen, said the businesses that consistently achieve the best insurance outcomes aren’t necessarily those focused exclusively on negotiating the lowest premium, but those focused on becoming a better risk. He said insurers aren’t looking for perfect businesses, but for businesses that understand their risks, manage them effectively, and can demonstrate they’re taking the right actions to protect what matters most.

Two examples of risk being presented differently

Everywhen said the growing complexity of cyber threats, supply-chain disruption and business interruption means insurers are placing significant emphasis on resilience, risk governance and the controls a business has in place. The firm pointed to two cases where improving how risk was understood and presented, alongside relatively simple risk-management measures, helped secure cover that had previously been difficult or impossible to obtain: a sawmill and timber products manufacturer that had been unable to secure property and business interruption cover, and an online retailer struggling to obtain cyber insurance.

In both cases, Everywhen said it worked to identify and articulate controls the businesses already had in place, alongside introducing relatively low-cost improvements, rather than making radical changes to either business, which allowed the underlying risk to be presented differently to insurers.

Brady said he has seen clients achieve premium reductions of between 20% and 50% once a strong, translatable risk-management approach and story is built alongside improvements in coverage and insurer engagement. But he said those savings are typically a by-product rather than the objective, with the primary purpose of risk management being to build a stronger, more resilient business that protects its brand, balance sheet, cash flow, assets and people.

The case against waiting for the renewal notice

Everywhen argues one of the biggest mistakes businesses make is treating risk management as something to think about only once renewal approaches. Cyber resilience, business interruption planning, fleet risk, flood preparedness and health and safety can all shape the overall picture an insurer sees, and Brady said risk management doesn’t start at renewal, since waiting until that point may already limit how much a business can actually influence the outcome.

He said the strongest businesses take a year-round approach, regularly reviewing vulnerabilities, strengthening controls and building a clear, ongoing picture of how their risks are managed. Quality, detailed and focused risk-management information, he said, gives insurers the evidence to underwrite positively, and demonstrating that risks have been identified, considered, managed and mitigated gives insurers greater confidence when setting terms, capacity and pricing.

Everywhen said businesses approaching their next renewal should reframe the question they’re asking, moving from “how do we reduce our insurance premium?” to “how do we increase insurer confidence in our business?”

The wider read

The argument Everywhen is making here isn’t new in principle, brokers and risk advisers have long said that presenting risk well matters as much as shopping the market, but the framing is notably direct in treating price negotiation and risk management as competing priorities rather than complementary ones.

Everywhen itself is the rebranded successor to Towergate, giving this advice some weight from a business with direct visibility into how commercial renewals actually play out across a large book of UK clients.

Whether businesses take up the year-round approach Brady describes probably depends less on the logic of the argument, which is straightforward, and more on whether smaller and mid-sized businesses have the internal capacity to treat risk management as a continuous discipline rather than an annual scramble ahead of a renewal date.
Source

Most consumers can’t verify AI financial advice – and nearly one in five has paid for it

Eight in 10 UK consumers now use an AI assistant at least three times a week, and six in 10 use one to help make decisions – a shift that is already reshaping how people choose financial products. Research presented at Defaqto’s 2026 Data of Record conference found that more people now turn to AI-powered tools than to a provider or financial adviser when making those choices.

The numbers sit alongside a trust deficit that has not kept pace with adoption. One in five consumers actively distrust AI tools when choosing a financial product. Nearly one in five have already acted, or almost acted, on AI guidance that later turned out to be wrong.

Most striking is that 62% of consumers say they cannot judge whether AI guidance is accurate. A client who cannot evaluate that guidance cannot self-correct when it fails. The research, carried out by Savanta on behalf of Defaqto, suggests a substantial share of the market is making product decisions in exactly that position.

Data quality is the hidden variable

Mike Piddock, managing director and interim CEO at Defacqto, told delegates that greater reliance on AI increases rather than reduces the importance of data quality. Firms need confidence in where data has come from, how it has been structured, and whether it gives a broad enough view of the market.

Defaqto has a commercial interest in that argument – its Star Ratings business depends on independently verified data. But the point carries more weight beyond the conference room than it might at first appear: AI outputs are only as reliable as the information they draw on, and consumers have no direct way to assess either.

Alex Ward-Booth, director at Savanta, compared the challenge to the California Gold Rush. Success there depended on distinguishing genuine gold from fool’s gold, and those who could not tell the difference lost their stake.

The human connection question

Keynote speaker Emma Boardwell, founder of Emotional Finance, argued that firms will need to “zig towards speed, efficiency, automation and AI in order to compete” while also “zagging towards human connection in order to differentiate and matter.”

That framing maps onto what insurance-specific research has been showing. The 2026 Guidewire European Insurance Consumer Survey found that only 30% of UK consumers are comfortable with AI making decisions about their insurance policy price. The three conditions consumers attach to any AI acceptance in insurance are human intervention, transparency, and independent regulation.

Those conditions describe what brokers already provide. A broker-assisted client has a named professional accountable for the advice, access to a broad market view, and a human to call when something goes wrong. A growing share of clients who turn to AI instead are getting none of those things, and many discover that only after the fact.

The Chartered Insurance Institute’s July 2024 Public Trust Index found that broker-assisted consumers report better insurance outcomes than those using price comparison sites or going direct, including on claims speed. As AI tools become a more common first stop for insurance decisions, that gap in outcomes is likely to widen before it narrows.

Source

Summer heat adds to a pothole claims problem already getting worse

Liability is rarely resolved cleanly

The insurance dimension extends beyond the motor book. Emma Fuller, partner at DAC Beachcroft and member of the Forum of Insurance Lawyers (FOIL) motor sector focus team, said the liability chain on pothole-related damage is rarely straightforward. “Drivers are expected to take reasonable care and adapt their driving to road conditions, while local authorities have a duty to maintain the public highway,” she said. “Whether a local authority is liable will often depend on what it knew, or ought reasonably to have known, about a defect and the adequacy of its inspection and maintenance regime.”

Source

IUA rebrand arrives as Jones reshapes leadership and claims focus

Chris Jones became IUA chief executive on May 1, 2025 and succeeded Dave Matcham, who retired after 20 years leading the organisation. Since taking over, Jones has restructured the IUA’s senior leadership, overhauled its approach to claims, and launched a talent programme that directly impacts the practitioners who will be processing and negotiating claims on behalf of London company market members for the next three decades.

Source

Silicon Valley’s AI ‘extinction’ panic lands on a market that’s already nervous about the risk

The London market has been building its own guardrails too. The Lloyd’s Market Association, working with Barnett Waddingham, has published an AI Adoption Toolkit to help managing agents build governance frameworks as AI moves from pilot projects into core underwriting, reserving and claims work. Sanjiv Sharma, the LMA’s head of actuarial and exposure management, said the market’s focus is now shifting toward how AI “is implemented and governed in practice,” rather than whether to adopt it at all. On the composite side, the ABI’s AI guide sets out five principles; accountability, transparency, fairness, safety, and contestability and redress  that member firms are expected to apply. 

Source

Lloyd’s lobbies for delay as UK’s ban on insuring Russian LNG tankers approaches

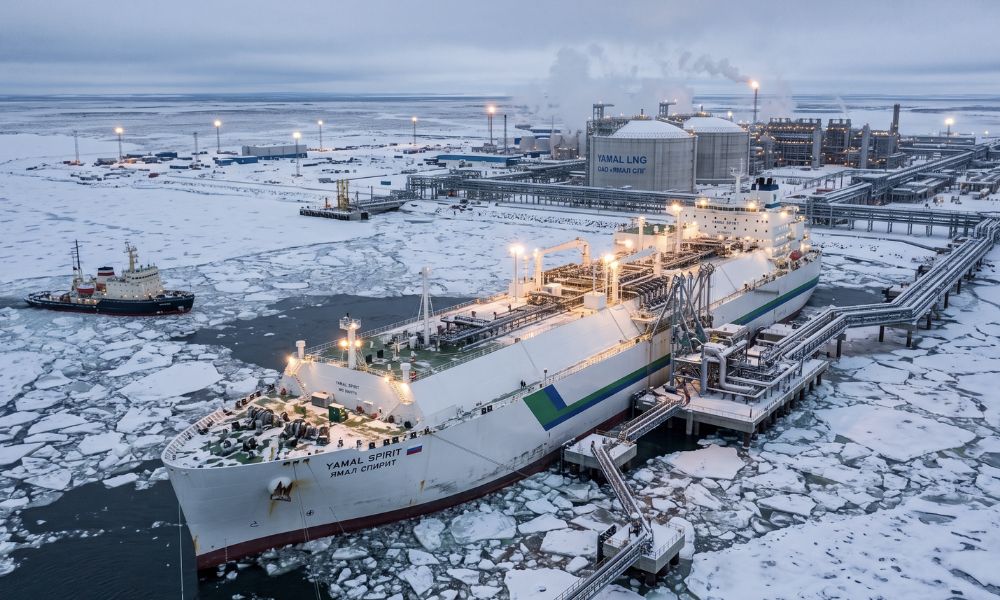
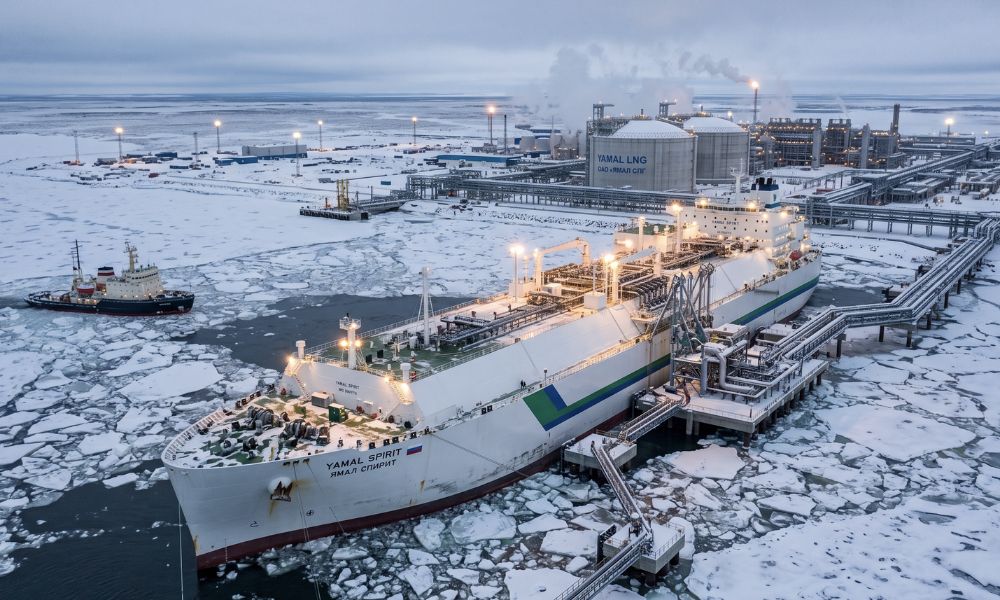
NorthStandard, the world’s second-largest P&I club following its 2023 merger with the Standard Club, continues to insure the Clean Planet, Clean Ocean and Clean Vision. The three vessels, owned by Greek shipping group Dynagas, were added to the UK’s Russia sanctions list in October 2025. They remain among the only EU-owned ships still serving Russia’s Yamal LNG plant in the Arctic, which has kept exporting large volumes of gas throughout the war.

Source

Life insurers face wording gap if assisted dying bill passes

In group risk schemes and multinational benefit arrangements, different legal positions across territories raise questions about consistent outcomes for policyholders in similar circumstances. Dunn said insurers may need “clearer, modernised wording to ensure consistent outcomes,” noting that cross-border policies would need to be tailored to each jurisdiction’s legal position. “While a generation ago that may have been boilerplate, recent changes mean an individualised approach is required,” he said.

Source

MNK Group lands first EU carrier with capital injection into ETU

What MNK is acquiring

ETU is authorised across eleven non-life classes in Denmark, covering property, general liability, motor, marine hull and liability, cargo, accident, legal expenses and assistance. The carrier is based in Rødekro, Southern Jutland. It transferred its private customer book to Forsia Forsikring in November 2024, a portfolio carrying approximately DKK100 million in annual premiums.

Source

Specialty deals hit record share as UK broker M&A shrinks

Why fewer brokers are selling

Buyer appetite has not disappeared. Thirty-two different buyers have acquired UK targets in 2026, and good businesses are still attracting interest. Several newly refinanced domestic consolidators have stepped up, including Jensten Group, JMG Group, and Seventeen, alongside overseas buyers such as Odealim, AUB, DOXA and ANV.

Source

contact us