

Businesses approaching renewal should stop asking simply how to bring the price down and start asking how to become a better risk, according to Everywhen.
With UK businesses facing continued pressure from employment costs, business rates, energy bills and wider operating expenses, the insurer and risk advisory group says reducing premiums understandably becomes a priority, but warns that an excessive focus on price can cause businesses to overlook the single biggest factor shaping their insurance outcome: how their risk is understood, managed and presented to insurers in the first place.
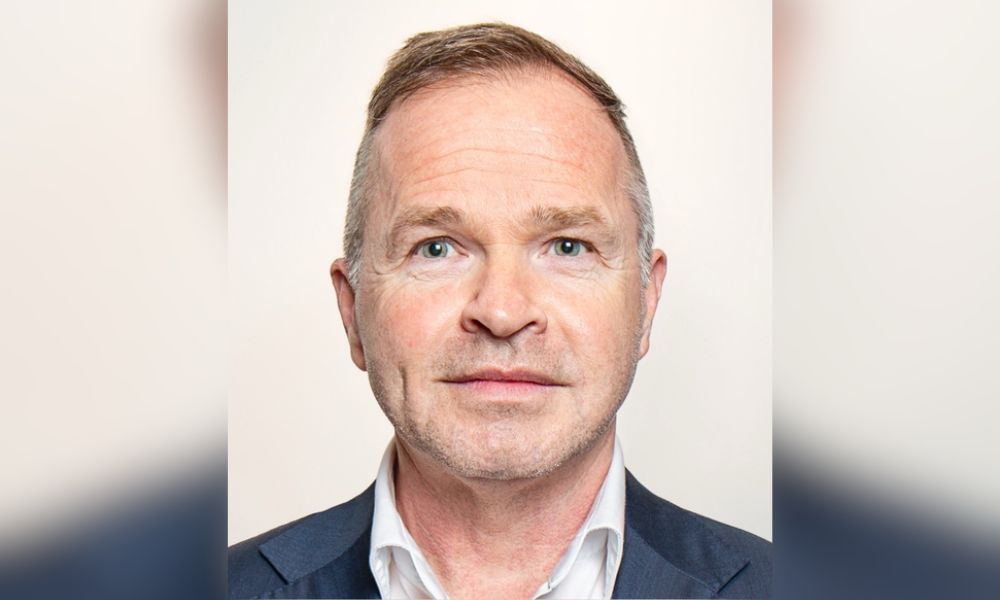
Chris Brady (pictured), chief executive of corporate, international and risk advisory services at Everywhen, said the businesses that consistently achieve the best insurance outcomes aren’t necessarily those focused exclusively on negotiating the lowest premium, but those focused on becoming a better risk. He said insurers aren’t looking for perfect businesses, but for businesses that understand their risks, manage them effectively, and can demonstrate they’re taking the right actions to protect what matters most.
Two examples of risk being presented differently
Everywhen said the growing complexity of cyber threats, supply-chain disruption and business interruption means insurers are placing significant emphasis on resilience, risk governance and the controls a business has in place. The firm pointed to two cases where improving how risk was understood and presented, alongside relatively simple risk-management measures, helped secure cover that had previously been difficult or impossible to obtain: a sawmill and timber products manufacturer that had been unable to secure property and business interruption cover, and an online retailer struggling to obtain cyber insurance.
In both cases, Everywhen said it worked to identify and articulate controls the businesses already had in place, alongside introducing relatively low-cost improvements, rather than making radical changes to either business, which allowed the underlying risk to be presented differently to insurers.
Brady said he has seen clients achieve premium reductions of between 20% and 50% once a strong, translatable risk-management approach and story is built alongside improvements in coverage and insurer engagement. But he said those savings are typically a by-product rather than the objective, with the primary purpose of risk management being to build a stronger, more resilient business that protects its brand, balance sheet, cash flow, assets and people.
The case against waiting for the renewal notice
Everywhen argues one of the biggest mistakes businesses make is treating risk management as something to think about only once renewal approaches. Cyber resilience, business interruption planning, fleet risk, flood preparedness and health and safety can all shape the overall picture an insurer sees, and Brady said risk management doesn’t start at renewal, since waiting until that point may already limit how much a business can actually influence the outcome.
He said the strongest businesses take a year-round approach, regularly reviewing vulnerabilities, strengthening controls and building a clear, ongoing picture of how their risks are managed. Quality, detailed and focused risk-management information, he said, gives insurers the evidence to underwrite positively, and demonstrating that risks have been identified, considered, managed and mitigated gives insurers greater confidence when setting terms, capacity and pricing.
Everywhen said businesses approaching their next renewal should reframe the question they’re asking, moving from “how do we reduce our insurance premium?” to “how do we increase insurer confidence in our business?”
The wider read
The argument Everywhen is making here isn’t new in principle, brokers and risk advisers have long said that presenting risk well matters as much as shopping the market, but the framing is notably direct in treating price negotiation and risk management as competing priorities rather than complementary ones.
Everywhen itself is the rebranded successor to Towergate, giving this advice some weight from a business with direct visibility into how commercial renewals actually play out across a large book of UK clients.
Whether businesses take up the year-round approach Brady describes probably depends less on the logic of the argument, which is straightforward, and more on whether smaller and mid-sized businesses have the internal capacity to treat risk management as a continuous discipline rather than an annual scramble ahead of a renewal date.


