Category

Insurance news

Aon’s debt nearly doubles as USI close approaches

Strong organic growth masks a balance sheet in transition as Aon prepares to close its US$17 billion acquisition of USI Insurance Services

Aon’s debt nearly doubles as USI close approaches

Aon’s third-quarter results show a business performing solidly on every revenue metric that matters. Organic revenue grew 6% in the quarter, with commercial risk and reinsurance each up 7% and health solutions up 6%. Adjusted operating margin expanded 70 basis points to 27.0%. Adjusted earnings per share rose 10% to US$3.36.

The balance sheet is less tidy. Long-term debt stood at US$14.66 billion at the end of 2025. By September 30, it had risen to US$26.32 billion, an increase of approximately US$11.66 billion in nine months. The jump is almost entirely attributable to the financing of Aon’s US$17 billion acquisition of USI Insurance Services from KKR, which is expected to close before the end of the year.

In September, Aon issued US$13.5 billion in senior notes across seven tranches, with maturities running from 2029 to 2056 and coupons ranging from 5.35% to 6.45%. The proceeds are currently sitting in short-term investments on the balance sheet, which jumped from US$1.6 billion to US$13.3 billion over the same period, awaiting the deal’s close. Once USI is absorbed, Aon will have completed two acquisitions totalling approximately US$30 billion in two years, following its US$13 billion purchase of NFP in April 2024.

Buybacks paused, restructuring accelerating

Aon repurchased no shares in the third quarter despite holding US$7.7 billion of remaining buyback authorisation, and has told investors it will prioritise debt repayment over shareholder returns as it targets a leverage ratio of 2.8x-3.0x within approximately 24 months of the USI close. The dividend continues, but the broader capital return programme is effectively suspended.

The Accelerating Aon United restructuring programme, meanwhile, generated US$93 million in charges in the quarter, up 191% on the same period last year. The programme was launched in 2023 to streamline operations, cut headcount and consolidate real estate.

Aon describes the driver as “primarily costs related to workforce optimisation,” which is headcount reduction. The timing is notable: NFP integration costs were described as “substantially completed” at June 30, and USI has not yet closed. The restructuring charge spike suggests Aon is rationalising its combined workforce across the existing business and NFP simultaneously, ahead of adding USI’s 10,500 staff.

The programme was initially designed to deliver US$350 million in annual savings by end-2026, with total cash charges of approximately US$900 million over three years. Nine-month charges in 2026 already stand at US$281 million.

Ratings pressure

S&P Global affirmed Aon’s A- issuer credit rating after the USI announcement but moved the outlook to negative, stating that a downgrade remains possible if leverage does not return to its base case within two years of the close. Fitch separately assigned a BBB+ rating to the new senior notes themselves and placed that rating on negative watch. Both signals reflect that Aon is carrying substantially more debt than it has historically, at a moment when it must also integrate two major acquisitions and retain the broker talent that makes both businesses valuable.

According to KKR, USI’s revenue nearly tripled under its nine-year ownership through a combination of organic growth and more than 90 acquisitions. Retaining that network through a change of ownership and integration with NFP is the execution risk S&P and Fitch both flag in their ratings commentary.

Aon frames USI as the next stage of the same middle-market thesis it deployed with NFP: buying a PE-backed broker platform and integrating it onto Aon’s shared services and analytics infrastructure. The deal is expected to dilute adjusted EPS in 2027 before turning accretive in 2028, with US$395 million in projected annual run-rate synergies.

Organic performance holds

The operating results that fund all of this remain strong. Commercial risk segment’s organic growth of 7% in the quarter was driven by North America and EMEA, with M&A services and core P&C performing particularly well. Reinsurance organic growth of 7% reflected strong treaty placements, though net market impact was unfavourable as pricing continues to soften.

Health solutions grew 6% organically, with particular strength internationally. Wealth solutions grew 4%, with demand for UK and EMEA retirement advisory work linked to ongoing regulatory change providing a consistent tailwind.

Total revenue for the nine months reached US$13.38 billion, up 4%. Free cash flow for the same period was US$1.94 billion.

“Our Aon United strategy continues to advance and differentiate our platform for clients,” said Greg Case, president and chief executive. “We enter the fourth quarter with significant momentum, reinforcing confidence in our ongoing ability to deliver sustained, differentiated performance.”

The fourth quarter is when all the deferred consequences land at once: the USI close, the debt on the books, the integration beginning and the first real test of whether the synergy projections survive contact with reality.

Source

‘A little too London-centric’ – insurance’s dementia campaign looks beyond the Square Mile

With more than £13m raised, Insurance United Against Dementia wants regional brokers, reinsurers and life and protection firms to play a bigger part in its next phase

‘A little too London-centric’ - insurance’s dementia campaign looks beyond the Square Mile

When Insurance United Against Dementia (IUAD) launched in 2017, its founders were not sure whether the industry would give a couple of thousand pounds or a great deal more. Nine years on, the campaign has raised more than £13m for Alzheimer’s Society, with around 150 firms now committed to it year after year. 

Benedict Burke (pictured), one of its three co-founders, puts that down to how the market works. Insurers, brokers and loss adjusters may compete hard, he said, but they also trade with one another every day, and IUAD was built on the relationships that grow out of that.  Ahead of Insurance Day for Dementia on 26 November, though, he is candid about where that network has yet to reach. 

“We think we have been in the past a little too London-centric,” he said. 

Beyond London 

The IUAD board has 12 members, each with a specific remit, and will introduce a dedicated regional markets remit for 2027–28, Burke said. Engagement in Bristol and Manchester is growing, and he wants more brokers, insurers and the wider supply chain, from lawyers and engineers to forensic scientists and loss adjusters, involved wherever regional trading markets are concentrated. 

That means finding people prepared to lead locally, because the campaign runs on relationships. “It’s all about who do you know and how you can engage with them and how you can bring the proposition forward and how you can make the ask politely but with purpose,” he said. 

London is not the only gap. Life and protection firms are taking part in growing numbers, reflecting the sector’s exposure to an ageing population, but Burke sees considerable room to deepen their involvement. Reinsurance partnerships have grown too, though not yet at the scale he believes is possible. He framed both as an open invitation to leaders in those sectors. “Dementia has no boundaries, and therefore nor do we.” 

Why the ask is hard to refuse 

Much of the response comes down to shared experience. Someone in the UK develops dementia every three minutes, Burke said, and many of those working across the market have seen its effects in their own families. His mother, Betty, a schoolteacher, died of Alzheimer’s, and when he talks about her, others often talk about their own. That common ground, he said, is why most people asked over a drink at an industry event to get involved find it “a difficult no”. 

The campaign also holds itself to account. Its board asks itself what Burke calls the “so what” question: what will the money actually do? From the outset, the founders committed never to charge an expense, personally or collectively, against the funds raised, so every pound goes to Alzheimer’s Society. 

IUAD’s funding commitment to the UK Dementia Research Institute between 2018 and 2025 helped support research into blood biomarkers, which could offer a cheaper, more accessible route to diagnosis than brain scans. Industry contributions to Alzheimer’s Society’s Covid-19 Support Fund also helped launch its Companionship service, which made more than 140,000 calls to over 5,000 people affected by dementia between 2021 and 2025. 

From awareness to action 

Burke admits he was once sceptical about how sincere corporate social responsibility really was. Working with his own colleagues changed his mind. The most dementia-aware firms, he said, invite IUAD in, give staff time for Dementia Friends sessions, and, where appropriate, train claims handlers and contact centre teams to recognise when a customer is struggling. 

Firms new to Insurance Day for Dementia can get a toolkit from Alzheimer’s Society, join its Lunch & Learn webinar, and have funds raised by 4 December matched by the Z Zurich Foundation up to £100,000. 

Speaking personally rather than for Alzheimer’s Society, Burke said helping employees diagnosed with dementia stay in work should be a legal right as well as a duty of care, balanced against firms’ commercial needs. 

Burke also has a longer-standing frustration; that insurance is too often maligned. By 2030, he wants government and the public to recognise the industry’s contribution, and other sectors to copy the model, as Sports United Against Dementia already has. The more immediate task is taking the relationships that built IUAD in London out to the regions, and into the reinsurance and protection markets. 

Source

ATE insurers likely to wait out Man City appeal before backing compensation claims

Burnley’s award against Everton gives underwriters a roadmap, but tying a rule breach to lost results and revenue remains the hard part

ATE insurers likely to wait out Man City appeal before backing compensation claims

Rival clubs and players considering compensation claims against Manchester City may have to wait until the club’s appeal is resolved to secure after-the-event (ATE) insurance, according to a specialist litigation insurance underwriter.

The Premier League announced on September 29 that an independent commission had found City in breach of more than 100 of its rules. City lodged an appeal on October 1 and denies wrongdoing. Arsenal, Liverpool, Manchester United and Tottenham reportedly lodged notices in 2024 reserving the right to claim compensation, while players and agents are said to be exploring loss-of-earnings claims if the verdict stands.

Rocco Pirozzolo, managing director and underwriting director at Harbour Underwriting, said: “With a live appeal, this creates uncertainty, and so I expect underwriters would want to wait for the outcome of the appeal.”

A three-member appeal board will hear the case and can dismiss or allow the appeal, send it back to the commission, or alter any sanction or compensation order. Sanctions will be considered at a separate hearing.

Under Premier League rules, the appeal hearing should be held within 12 weeks of being lodged, with a decision due within 30 days of it ending, which points to late January if the timetable holds. Sky Sports has reported the process could run later if City argue that the new appeal rules should not apply to their case.

A breach is only the first hurdle

Pirozzolo said the novelty of these claims may put them outside the appetite of some ATE insurers. For those willing to consider them, a finding that the rules were broken is only where the analysis begins.

“They know that the claimant has to connect that breach to a different sporting outcome and then translate that outcome into a financial loss,” he said.

That is the chain Burnley had to prove against Everton. In June, a Premier League commission ordered Everton to pay Burnley more than £35m in compensation and interest, finding that Everton’s breach of the Profitability and Sustainability Rules in 2021-22 gave it a sporting advantage that caused Burnley’s relegation. Burnley had sought around £51.7m, and the commission awarded £26m, with interest taking the total past £35m. Everton is appealing the decision.

For Pirozzolo, the award gives underwriters a roadmap for assessing such claims. The expert evidence Burnley relied on addressed both causation and the size of the loss, although Everton’s appeal leaves that roadmap under challenge.

Capacity and the cost of pursuing claims

These cases rely heavily on expert evidence, and Pirozzolo expects football clubs to “vigorously defend” them. They may therefore require significant limits of indemnity, although he believes the market has the capacity to provide them.

Third-party funding and dispute insurance are not only for claimants who could not otherwise afford to litigate. Premier League clubs and players with the means to bring claims can use them too.

Pirozzolo said “lawyers advising their clients in respect of these cases should consider both funding and insurance as ways to enable these cases to be brought.”

For brokers placing ATE, the timing of the appeals and the strength of each claimant’s causation evidence are likely to shape when cover becomes available and on what terms. Until claimants can show how a rule breach changed a sporting outcome and what that cost them, underwriters will have little to price.

Source

£17.5M in fake returns, a flight to Dubai, and a fraud judgment that survives bankruptcy

The statements said Goldman Sachs. The money went somewhere else entirely

£17.5M in fake returns, a flight to Dubai, and a fraud judgment that survives bankruptcy

What happened: The High Court found a fund manager fabricated returns and awarded approximately £17.5 million

Who’s involved: Coleman Capital LLP (in liquidation), its Gibraltar holding company, and their controlling director

What’s at stake: Approximately £17.5 million in investment money, none of which has been returned

Why it matters: The fraud finding survives bankruptcy, putting PI and D’O underwriters on notice

Where it stands: Summary judgment entered October 9, 2026; remaining claims stayed

The monthly statements looked fine. They showed steady returns, Goldman Sachs custody, and a segregated account with the investor’s name on it. The custodian’s own trading records told a different story: the entity that actually controlled the money – Coleman Asset Management Group – carried a running negative balance with the custodian that had blown past US$18 million by the end of 2023.

That gap between what an investor was told and what was actually happening with his money is at the centre of a judgment handed down on October 9, 2026, in the High Court’s Business and Property Division. The court granted summary judgment of approximately £17.5 million against Coleman Capital LLP, its controlling director, and a Gibraltar-registered holding company, Coleman (Europe Holdings) Limited. The basis: fraudulent misrepresentation – in plain terms, deliberate deceit.

The investor, a chartered surveyor and businessman, placed a total of approximately £17.5 million with the firm and its director between September 2020 and April 2024. The money fell into three pools: roughly £3.7 million for what was described as the Coleman Funds, about £800,000 in equities transferred from a Kleinwort Hambros portfolio, and £13 million earmarked for a LIBOR-linked deposit account.

Goldman Sachs on paper, a deepening hole in practice

The pitch, as documented in emails, presentations, and a formal offering memorandum, was elaborate. The investor was told his money would go into a Cayman-based fund using Goldman Sachs as prime broker, independently administered, audited annually by BDO, and held in a segregated custodian account. He was told he could withdraw at any time.

None of that happened. Evidence from the custodian, Linear Investments Ltd, showed the money was instead routed to Coleman Asset Management Group – another entity controlled by the same director – and used for proprietary trading and to pay out other investors who were redeeming. The director himself conceded in a witness statement that “the accounts were not fully segregated in the way originally described and that the investment profile differed from initial expectations.”

Meanwhile, the investor received monthly statements bearing the firm’s name and FCA registration number, each purporting to show his balances growing with positive returns. The custodian’s trading data painted the opposite picture: Coleman Asset Management Group’s running balance with the custodian was negative by more than US$5 million at the end of 2021, nearly US$11 million by the end of 2022, and over US$18 million by the end of 2023. Data from the custodian showed the director instructed transfers to that entity on the same days the investor’s money arrived.

The investor’s case was that the director must have known the monthly statements he sent were untrue. In his evidence, the director did not say the statements were true, gave no explanation for them, and did not address them at all. The court, in granting summary judgment, found the defendants had no real prospect of a successful defence.

No defence, no money, no explanation

When the investor asked for £1 million back in March 2025, nothing came. When he asked for everything back, nothing came either. The court put it plainly: “Disaster may unfortunately strike the most careful of investment managers. But honest managers do not usually lose everything.”

The defendants never filed an acknowledgement of service or a defence. The director filed a witness statement denying fraud and blaming the losses on third-party failures – principally a default by a company called Omnia Group Holdings AG and the conduct of the custodian. But the court found the defence unparticularised and unsupported by any documentation. In the modern finance world, the court observed, “it is inconceivable that such documentation would not exist and be available to the defendants.”

There was one more detail the court did not overlook. The director, who had been based in the UK throughout the investment relationship, moved to Dubai after proceedings were issued. “The obvious inference,” the court said, “is that he is running away.”

The judgment that follows you

The court entered summary judgment on fraud specifically – rather than a simpler default judgment – for enforcement reasons. Under the Insolvency Act 1986, a debt arising from fraud is not wiped out when someone is discharged from bankruptcy. The director had been bankrupt from August 2025 to August 2026, but the fraud finding means the £17.5 million liability follows him regardless.

The court also set aside the loan agreement between the parties, removing a contractual cap that would have limited liability to 120% of the loans made. A cap in a contract obtained by fraud does not survive once the contract is unwound.

Damages were assessed at £3,669,796.42 for the Coleman Funds, £814,871.64 for the transferred equities, and £13,000,000 for the LIBOR deposit monies. Coleman Capital and the director are liable for the full amount; the Gibraltar holding company is liable only for the Coleman Funds portion. The remaining claims – including claims to trace and recover the actual assets – were stayed, with the investor’s legal team noting the full picture of where the money went remains incomplete.

For PI and D&O underwriters providing cover to regulated investment managers, this is a textbook scenario: fabricated performance reporting, misappropriated client funds, a controlling director who is the sole point of failure – and a fraud judgment that no insolvency process can extinguish.

The claims in this case have been determined by the High Court on a summary judgment application. The court found the defendants liable for fraudulent misrepresentation on the balance of probabilities. The remaining claims to trace and recover assets have not yet been adjudicated. No recovery from the settled fourth party, Linear Investments Ltd, has been disclosed.

Source

Independent brokers face a battle to recruit and retain staff

In this Insurance Business TV report, independent UK brokers discuss the recruitment and retention pressures facing their businesses, from losing staff to larger rivals to leaving vacancies unfilled while they seek the right candidate. They share their approaches to developing new talent and explain why changing perceptions of insurance needs to start before young people enter the workplace.

Source

‘Scotland is a foreign country’ for insurers, and UK divergence could widen the gap

Higher claimant costs and bereavement damages already shape Scottish claims reserves, regardless of what happens to the union

'Scotland is a foreign country' for insurers, and UK divergence could widen the gap

For the first time since devolution began, Wales, Scotland and Northern Ireland all have first ministers who want to leave the UK. Last month all three signed a memorandum declaring that “Westminster’s time is coming to an end”.

No vote is imminent. Andy Burnham has said a second Scottish referendum remains off limits, and Plaid Cymru has ruled out a Welsh vote before 2030.

For insurers and brokers, though, the practical differences already matter. Scotland’s separate legal system shapes claims costs, reserving and settlement strategy today.

Where Scottish claims cost more

Andrew Lothian, partner in DWF’s major injury and casualty team in Scotland, said the biggest difference is in costs on lower-value personal injury work, whether road traffic accidents or employers’ and public liability. Based on recent data, he estimated that roughly £2 goes on claimants’ costs for every £1 of damages in lower-value Scottish personal injury claims.

He contrasted that with England, where fixed recoverable costs apply to low-value whiplash-type motor injuries. Scotland has no equivalent, which he said gives claimant firms a margin on that work that is not available in England.

Fatal claims are the second gap. They are a small share of the total, but Lothian said a widow in Scotland might receive around £120,000 or more, while the statutory bereavement award in England and Wales is £15,120.

A third difference concerns the treatment of dishonest claims. Scotland has qualified one-way costs shifting, which protects claimants who litigate, and that protection can be lost for fraudulent conduct, manifestly unreasonable behaviour or abuse of process. What Scotland lacks is the fundamental dishonesty defence that applies in England and Wales, and efforts to bring it in through test cases have not succeeded.

“It’s likely that it’s going to need legislation rather than somebody trying to persuade a judge that it’s a good idea,” Lothian said.

The rules that introduced qualified one-way costs shifting are due for review after five years, which Lothian said should happen around now. The case for bringing fundamental dishonesty and fixed recoverable costs to Scotland continues to be made, but he said there is little appetite for either at present.

Those differences often feed straight into reserves. Where a fatal claim could be litigated or presented in Scotland, insurers need higher damages reserves, and at the lower-value end, claimant cost reserves run higher than in England and Wales.

The continued accrual of claimant costs gives insurers an incentive to settle early, while reducing the financial incentive for claimant firms to do so. Lothian described many Scottish claimant solicitors as highly skilled at staying within the rules while keeping their businesses highly profitable.

What independence would change

Further divergence is hard to call while Scotland remains part of the UK. Full independence could look like the position in the Republic of Ireland, with policies covering one jurisdiction only.

If cover became restricted to one jurisdiction, brokers placing business for clients on both sides of the border would need to scrutinise territorial limits. The bigger open questions, Lothian said, are structural, including whether a UK-wide single market would cover financial services and who would regulate in Scotland.

Scotland would at least start with the legal infrastructure in place, from its own legislature and courts to its own legal qualifications, which Lothian said leaves it able to be “fairly nimble”. He said Northern Ireland, also its own jurisdiction, is probably the closer comparison, while an independent Wales would likely start with English law and diverge over time.

Lessons from the last split

For now, Lothian said, client questions about independence remain informal, because nobody knows what it would look like in practice. His standing advice to insurers and brokers is simpler.

“If you forget every single thing I’ve said to you, as you probably will, and you only remember one thing, remember that Scotland is a foreign country,” he said. Firms that try to handle Scottish claims “in an English way” are the ones that come unstuck, he said, while those that recognise the difference know to bring in local help.

The structural questions, he said, would need answers ready in advance rather than a decision to “just cut it off and see what happens”. Brexit showed the scale of restructuring a split can force. By early 2019, the ABI estimated UK insurers had moved around 29 million contracts and set up about 40 new EU hubs.

Whatever the constitutional outcome, insurers already need to reflect Scotland’s distinct claims environment in their reserves and settlement strategies.

Source

Commercial contracts still need a broker, not a question set

A contract clause, policy restriction or warranty can change whether a commercial policy meets a client’s needs. For Matthew Mawson (pictured), managing director of Sheffield-based Eximia Broking, those details are exactly where automation should stop and a broker’s advice should begin. His clients in road transport, construction and plant hire, he said, need more than an online question set to get it right.

“Back office and presentations should be automated as much as possible,” Mawson said. “However, client-facing, advising and risk evaluation should be carried out by the broker.” He said understanding commercial risks requires time spent with the client and their business, something that cannot be “undertaken by AI.” Without that understanding, brokers cannot identify the most suitable cover.

The British Insurance Brokers’ Association and Markel have taken a similarly measured line since 2025, when their joint AI guide warned against treating the technology as a fix for everything. A caution that has since grown into the Broker AI Academy, whose founding cohort of 20 brokers completed its first two-day session in Leeds earlier this month.

The same distinction is playing out across the market. Some brokers argue that personal relationships are becoming more valuable as AI takes over routine work. “You might as well be a comparison site,” said Charlie Hicks, managing director of EIC Insurance Services. “If you’re doing that, you’ve added nothing to the relationship.”

For clients in road transport, construction and plant hire, Mawson said the gap between a portal and a broker shows up in contract detail. A portal cannot provide the depth and knowledge required to properly insure all the risks, whereas a broker with the right experience knows which questions to ask. That includes understanding whether a job falls under the Joint Contracts Tribunal (JCT) suite used across UK construction, the Construction Plant-hire Association (CPA) model conditions for hired plant, or the Convention on the Contract for the International Carriage of Goods by Road (CMR), which has carried the force of law in the UK since the Carriage of Goods by Road Act 1965. Mawson said brokers also need to flag what cover uplifts are required, which policy restrictions should be negotiated out and which warranties a client needs to be aware of.

“I’ve seen numerous examples of policies bought online that are not fit for purpose,” he said. Question sets are often ambiguous, clients don’t understand the consequences of a wrong answer, and once a policy is bought, the document is rarely read properly until something happens, by which point it is too late.

Other senior figures describe the same problem from the insurer side. Speaking at AIRMIC 2026, Stuart Sutherland, head of UK retail at Liberty Specialty Markets, described a furniture retailer whose policy was written as if the business were still a simple shopfront, when it had grown to design, manufacture, deliver and install its own products – several distinct exposures sitting undetected under one programme. “Back to basics means asking: tell me about your business,” he said. “What keeps you up at night? Before we talk about coverage.”

The cost of providing advice

Mawson does not think a people-first model is necessarily slower than an automated one, provided the right information and a clear understanding of risk and objectives are established from the outset. He said higher acquisition costs can squeeze margins, although stronger renewal retention should help offset them.

“A fully automated process works for scaling low-value products that churn. People-first helps retention, thus smoothing margin, and provides recommendations that help scale a business.”

The starting point is whether the client needs advice and how complex their business and insurance requirements are, Mawson said. Automation can smooth the client journey, “but don’t leave the advice to an AI data centre.” Those needs should determine where automation stops and a broker steps in.

Source

Charities taking on new activities risk outgrowing their insurance

A new project can change an insurer’s appetite even when it feels like a natural extension of a charity’s work

Charities taking on new activities risk outgrowing their insurance

Men’s Sheds are community groups built around practical workshop activities. “Their purpose is dealing with social isolation,” said Tim Larden, sales and marketing director at UK charity insurance broker Access Insurance, part of Benefact Group. 

As those activities develop, groups may overlook the need to revisit their insurance. A group might buy a policy, he said, “and then put that on the shelf and think, well, that’s our insurance sorted.” Then a new project comes along. Larden has seen Men’s Shed groups build canoes and take on hot tools, and they may not have spoken to their insurer about either. 

An insurer comfortable with the hand tools a group started out with might not accept fixed machinery, hot tools or bicycle repair. Repair cafés, where volunteers help repair items people bring in, raise a similar issue: general repairs may fall within an insurer’s appetite, while work on white goods brings the risk of a failed repair causing a fire. 

“It’s not a natural distinction to necessarily make that this activity was okay, but this activity actually is not okay with your current insurer,” Larden said. 

When buyers don’t know what to disclose 

Many people arranging insurance for charities draw on their experience of buying car, home or travel cover, Larden said. That can lead them to assume that if they were not asked about something, they do not need to mention it. 

Charities arranging non-consumer insurance are subject to the duty of fair presentation under the Insurance Act 2015. Brokers need to explain that responsibility, he said, so they understand that “even if it doesn’t appear on a proposal form from an insurer, we should talk about everything that really is material to your organisation.” 

Sector knowledge also helps brokers explain unfamiliar activities to insurers. When Larden first sought cover for Men’s Sheds, insurers “weren’t that keen”, he said. His case included the sheds’ limited opening hours, perhaps a couple of sessions a week, and some insurers eventually came on board. 

Renewals that tell a story 

Charities tend to change more than an average business. While a traditional commercial renewal might focus on income, wages and employee numbers, a charity could receive a £1 million grant from a local authority or NHS trust to deliver a major project. 

Some work with people with complex needs, rely on volunteers and hold sensitive data. Changes to a charity’s activities can alter its insurance needs, even when those changes are less obvious than a new building or a large grant. 

Open questions can reveal more than the figures alone, Larden said – what new projects a charity has, what it is proud of, how its services are changing and what pressures it is under. 

“You tend to then get a little bit more of a story, and that deeper conversation benefits everybody,” Larden said. 

That gives the client more relevant advice and the insurer better information, while allowing the broker to look beyond processing a renewal. 

Bringing the broker in early 

Property acquisitions make the value of early discussions particularly clear. It is not uncommon for a local authority to hand a charity a building that may be borderline derelict, Larden said. It may initially be unoccupied or require renovation work, creating a need for specialist cover or risk management. 

Clients are encouraged to make their broker the “first port of call and not the last line of defence”, he said, but requests can still arrive the day before a charity exchanges contracts on a property. 

“Giving an underwriter time to understand something and ask sensible questions and work constructively with us is a much better position than presenting an underwriter with an urgent fait accompli,” Larden said. 

The same principle applies to a new workshop activity or service: involving the broker while plans are taking shape gives the charity time to establish whether its insurer can accommodate the change and what protection it needs. 

Source

What do people really mean by ‘digital trading’?

We like to have a big idea each year at LIIBA. Something that goes above our day-to-day role of lobbying, training and market support and expands on a relevant theme of the time. Over the years we have looked at such things as how our members were developing solutions to the climate crisis; what would be the future of face-to-face negotiation in a post COVID world; and the contribution of insurance distribution to the global economy. This year we decided to try and define what people really mean by “digital trading” – a phrase much used but seldom with a concrete concept of what it might actually entail. 

In Trust Imperative – How Digital Trading Can Revolutionise Client Outcomes But Why Humans Must Stay in Control we accept that the rapid technological advances we are seeing do have the potential to completely overhaul how we service client needs. But it will only work if it is managed in a way that understands what the relationship between client and broker really is. We don’t sell products, we provide an experience. Clients look to our members’ risk management expertise to provide the peace of mind that allows them to take bolder, innovative decisions that drive economic growth. So, whilst technology has a huge role to play in providing a more efficient and personalised solution, it will need humans to remain in control to provide reassurance that the solution is the right one. Trust will continue to be the foundation upon which our market is built. I commend the work to you, and all episodes can be downloaded now on our website. 

But it is all fine and dandy having big ideas. What really matters is how we build on this to provide a suite of support for members trying to negotiate this new epoch – particularly the 80% of LIIBA members that are small businesses with fewer than 50 staff. So, what comes next? 

A challenge for small firms, without dedicated in house technical resource, is how do you go from AI (I use the term loosely) doing something clever to doing something useful. And this is especially true in the heavily regulated industry in which we work. Operationalising the new technology so that it delivers tangible, consistent efficiencies is not straightforward. This is an area where a trade association can help. We will start with a webinar (working title: how to go from ******* about on ChatGPT to becoming an AI driven business) to look at the basics. And we might explore a partnership with a suitable technology firm to provide an AI audit service for members who want to build on this.

One of the interesting findings from our research was that many members faced a common problem. They have employed brilliant data scientists, but they tend not to know a lot about risk. And they have brilliant risk analysts who might not be well versed in spotting patterns in data. So, it is sometimes only a serendipitous accident if these two professional groups converge on a practical proposal. We will explore the extent to which this is a result of a gap in the academic system in UK. Is there scope for sponsoring a combined data and risk course somewhere?  How can our schools and universities develop the rounded recruits we need? 

The report looks at how the ability to process real time data will see a move away from a static annual renewal process to a continuous analysis of client risk. And that this will require the development of new financial instruments to be able to trade risk day-to-day. That will have regulatory implications in that our members will need to be active in markets that may well sit beyond their current permissions. If this is to work, particularly for smaller firms, it will need a streamlined authorisation and supervision model to support it. Smaller firms will not be able to cope with the regulatory burden of being separately regulated as an insurance intermediary and a derivative trader for instance. We need to find a way to recognise their hybrid role – especially as this new way of approaching client risk will enhance London’s international competitiveness – something our regulators are now duty bound to encourage. So we will begin discussions with FCA on how we flesh out this idea and work together to find the right outcome. 

Technology is already speeding up processes in our market – especially around the execution of the trade with the growth of automated follow facilities. This is going to create time for traders and we believe that will allow a renewed focus on growing the market by addressing the protection gaps that exist around the world. In our Innovation Imperative report launched last year, we estimated this at $2.5 trillion globally. This is a huge opportunity for London but it will require our members to have the right access to international markets to allow their magic to come to bear. So we will renew our work – through our global partnerships such as BIPAR (the European federation of insurance intermediaries) and World Federation of Insurance Intermediaries – to lobby for sensible, proportionate approaches to licencing that recognise the need of all economies to manage their risk by accessing global capital. Indeed, I am writing this article in Colorado Springs where I am attending the annual conference of Council of Insurance Agents and Brokers – our sister organisation in Washington DC with whom we work hand in glove. These relationships are going to be more and more important. 

With that, we have a plan to turn our big idea into ways in which we can grow and expand the impact of our membership across the world. A big idea can become a big concept. We better get on with it.

Source

Green buildings aren’t safer

00:00 – Mike Ward: do whatever it takes to win and retain business.
David Tilly: Had a mini flood out the front of my house yesterday afternoon.
Justin Warents: The greener building isn’t necessarily um spelling a lower insurance risk.
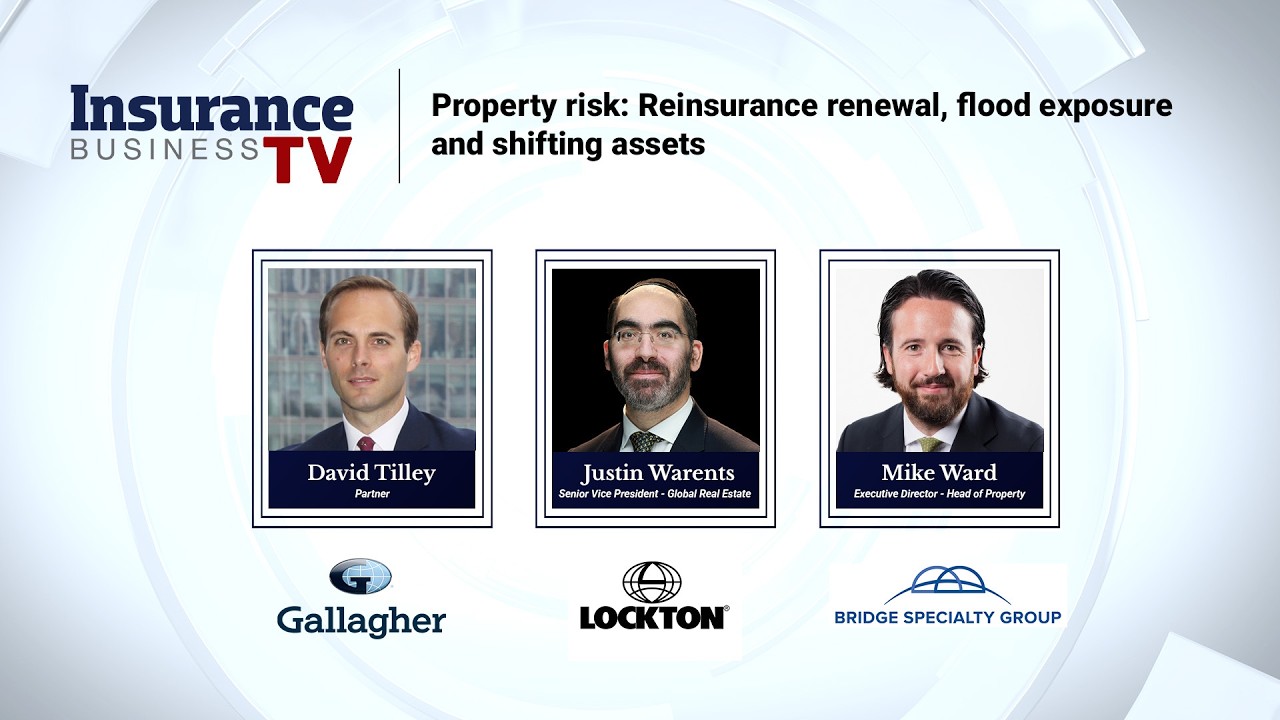
Paul Lucas: Hello everyone and welcome to the latest edition of our property insurance power panel. Now catastrophe modeling, inflation and data center risk were a focus last quarter. This session looks at what’s flowing down from the reinsurance renewal and into harder to place property risk along with the

00:28 – Paul Lucas: physical shifts reshaping the asset classes that insurers are covering. And to take us through it, we welcome back Justin Warents, senior vice president, global real estate at Lockton, Mike Ward, executive director, head of property at Bridge Specialty Group, and joining us for the first time, David Tilly, partner in real estate at Gala Specialty. So, welcome all. And to get us started, tell me how are the outcomes of the recent reinsurance renewal feeding through into primary property terms uh capacity as well and pricing of

00:59 – Paul Lucas: course. Uh Mike, what are you seeing?

Mike Ward: Yeah, good morning. So, you know, we are continuing to see the direct soft market uh sorry the direct insurance property market being very soft. There’s significant capacity available with existing insurers remains grow their current portfolios. you know deploy extra capacity if needed but also there is a lot of new entrance into the markets and MGAs which again continues to increase competition across the market you know this is obviously very

01:28 – Mike Ward: valuable for the buyers at the moment with insurers competing aggressively on pricing you know cover enhancements service offerings basically to do whatever it takes to win and retain business but from a reinsurance level you know we are seeing capital positions remain strong um which is obviously supported by a healthy balance sheet. You know, unfortunately, well, not unfortunately, but looking ahead, we see little evidence uh to suggest a meaningful hardening off of the London market and the property market. The only

01:57 – Mike Ward: way this is going to change if there’s a major significant loss or see series of major losses, you know, that particularly impacts insurers and the reinsurers balance sheets.
Paul Lucas: Yeah. And David, from your perspective, do you think reinsurers are willing to concede on rate?
David Tilly: Absolutely. Certainly from the January and the July uh renewals, it certainly seems to be the case still from a very basic economic perspective, we’re in a position where we’ve got an over supply versus uh the demand on there. So very

02:28 – David Tilly: basically that drives the financial contribution on it, but it’s also given clients the opportunity to broaden the terms that they’re receiving, not just focusing purely on price on there. So as we insurers start to concede on pricing and give away some of the coverage, naturally that flows through to the direct market on there. So as Mike was saying, it would need something quite considerable to uh influence the market direction between now and the end of the year on there. So I think from a

02:55 – David Tilly: client perspective, they can expect to enjoy a continued uh buyers market environment and really start to push those uh pricing and the uh and the coverage options available to them. And there and I think that will continue into the uh into the new year as I say unless something significant happens between now and then.
Paul Lucas: Yeah, agree with that just in that that reinsurance tailwind perhaps feeding through into the primary property market.
Justin Warents: Good morning, Paul. Good to be back on. Um yeah, I would agree with those

03:23 – Justin Warents: sentiments. Um certainly we’re seeing the reinsurance tailwind is now generally feeding through into the property uh primary property market. The January renewal, as David said, saw further softening in the property catastrophe reinsurance. We’ve got healthy level of capacity in the primary property market. So very much a uh a soft market uh still remains. However, you know, underwriting uh is not necessarily uh soft. You know, insurers are becoming increasingly sophisticated about what how they deploy their

03:58 – Justin Warents: capacity. So the clients are getting the best outcomes when they can demonstrate that they generally understand their assets. Um, ranging from cat exposure, valuation, construction, defense resilience, and business interruption.
[03:58 – 04:48]  Paul Lucas: I don’t know about the rest of you guys, but I’ve certainly been under the caution of some heavy rains lately, and it sort of provokes this question if you want because of course flood and coastal exposure zones have remained a persistent challenge,

04:24 – Paul Lucas: haven’t they? David, from your perspective, what’s the current state of availability and indeed affordability for property in in the particularly high-risk areas?
David Tilly: Uh, yes, I can share that sentiment, Paul. I had a mini flood out the front of my house yesterday afternoon. Um actually some of the uh bits that Justin just mentioned there around the reinsurance market is flowing into certainly into this question and that can be around evidencing your risk profiles to the insurer themselves

04:52 – David Tilly: because this is always an area of the market that is under constant scrutiny on there and I think this can come down to something very basic as the accuracy of your postcode uh on there. I know it sounds silly, but it can be the difference between you being at the bottom of the hill and the top of the hill. And that can really drive an insurer response to what your risk profile looks like. And one of the um areas that certainly we’re seeing insurers looking to do is yes, they want to help in clients on this. And yes,

05:19 – David Tilly: they want to start writing more of your client’s business, but at the same time, they recognize if there’s been an inherent um loss or I guess the program’s been affected by a coastal flood, how do we work with them to uh improve that risk profile? and some of the implementations from a risk management bery. So your help insurers helping with the client cost of improving those resilience certainly is something that we’re seeing creep back into the market now as some of the maybe

05:45 – David Tilly: you might say the softer market behaviors from an insurer perspective on there. So a lot of it comes down to is it available? Yes. Is it affordable? Depends on what your risk profile looks like. So what coverage is available also comes down to what your risk profile is like. So work with your broker, present your risk as clear as possible and be open to maybe implementing and deploying some capex to improve the risk profile of certain assets.
[05:45 – 06:47]  Paul Lucas: Yeah. And Justin, do you think this area around flood can be a little bit

06:16 – Paul Lucas: misleading sometimes?
Justin Warents: Yeah, I would say Paul that flow is probably one area where the general soft market that we’ve just spoken about can be uh a little bit misleading. Um there’s certainly more capacity across the property market but where there are the you know the highest flood and coastal exposures then insurers um do remain cautious um that’s not to say that cover cannot be achieved. Um but ultimately the underlying physical risk that remains uh is not going away. Um

06:46 – Justin Warents: so what’s really important is to make sure that um a broker gets well behind uh the position uh because insurers will want to know it’s not about just saying um is does this property sit in a flood zone? It’s you know what is the ground elevation like you know what are the flood defenses in place? What does the drainage look like? Has it had history of flooding? U what resilience measures have been installed? And with all of these uh questions with answers, then that does create an

07:18 – Justin Warents: opportunity to have a conversation with insurers take a view um you know model the flood zone uh properly using latest technology that’s available. So I’d say that good data, engineering information and evidence will certainly help to achieve a meaningful outcome for property owners.
Paul Lucas: Great tips from David and Justin here so far, Mike. But overall, would you say that flood is maybe still one of the more challenging perils in the UK market?
Mike Ward: Yeah, definitely is is evident is one of

07:49 – Mike Ward: the most challenging perils to get there. However, again to reiterate, there is capacity available. Insurers are heavily relying on their flood modeling tools. Um but again, you know, if organizations can demonstrate they’re doing as much as they can to potentially mitigate against a claim happening, you know, by putting in fluff barriers, elevating plant equipment, you know, just basically robust emergency planning, then insurers are willing to come to the table and work with a client to make sure that the cover’s

08:17 – Mike Ward: there in in the event of a claim.
Paul Lucas: Of course, a big discussion point right now is those net zero retrofits and those new green building materials which are changing the risk profile of commercial property. So, uh Justin, how are underwriters adapting to assess that?
Justin Warents: Okay. Well, first thing would we be to make the point that um you know insure the insurance industry is certainly not putting the brakes on when it comes to you know green and net zero. they’re very much in in favor and

08:46 – Justin Warents: recognize that, you know, modern developers are deploying and using that for good reason. But it’s also important to bear in mind that a greener building isn’t necessarily um spelling a lower insurance risk. So typically we’re seeing property owners introduce um things like um you know EV charging which is popular now the use of mass timber the number of buildings that have been developed that that has hybrid use of that um new insulation of facade uh systems all of this works towards net

09:18 – Justin Warents: zero but actually putting on um you know a blue roof or green wall doesn’t necessarily remove the risk. So, it’s really important that the broker works with the property owner to make sure that things like, you know, water damage exposures, the installation, um, who’s designed this, what’s the fire separation, all of these things will contribute to understanding the building better. And I think a really important point here is to make sure that you know from the outset before a property has uh at the

09:51 – Justin Warents: development stage, you know, developers and their professional advisers are taking the time to look at these nuances and testing what it looks like with and without so that they can get a more informed position. because sometimes making a subtle change will not necessarily have a large impact significant impact on an insurance premium and allows the proxy owner developer go along with their strategy. Um whereas for other things um consult consulting with the insurance market means that the risk engineers from the

10:24 – Justin Warents: insurers are able to provide some meaningful input towards things and um they end up getting a better steer on what that property premium would look like once the building has practically confused.
Paul Lucas: Such a good point that that Justin’s made there, isn’t it Mike? I mean greener is not necessarily safer. So from your perspective is there enough data in this area
Mike Ward: at the moment? you know there is there isn’t much long-term data so it is quite limited so that’s why you know we are

10:52 – Mike Ward: seeing insurers you know emphasize the requirement of you know quality of installation fire protections know there’s main procedures and contracts in place for the equipment itself you know again what Justin said there is just because it’s green it doesn’t make it safer or lower risk but again this will come in time when the loss data does come in uh because obviously it’s all fairly new and it’s not It’s not as comprehensive as the older building materials that have been used in the

11:19 – Mike Ward: past. So, it’s still a long way to go until we know the full impact of the, you know, net zero refits and the green building materials, what they’re going to cause to the market.
Paul Lucas: What you’re seeing, David, do you think that insurers actually want to support clients who are making these green steps?
David Tilly: Absolutely. And I think they’ve been vocal for a number of years, being wanting to work with clients, not just from um a global overview, but for their own personal perspective. they want to

11:45 – David Tilly: be partnering with uh clients that are moving into this net zero space. But with that, when you’re tweeting when you’re talking about retrofitting, you’re talking about a building that may have a loss record over the last 10, 15 years that could very well be jeopardized going forward with the introduction of heightened electrical risk, maybe introducing higher fire risk. I think Justin covered it off earlier. So, who are you partnering with from a contractor perspective? And a lot of this comes down to some of the very

12:13 – David Tilly: basics of uh insurance partnerships is don’t tell us when it’s just about to be completed. Get engaged with your broker, get engaged with your insurer, get engaged with the experts when you’re starting to considering this uh move into a retrofit and they will point you in the right direction. So we remove as many surprises as they possibly can be once you get to the PC element of a of a retrofit so you’re comfortable that the insurance is going to be in place what it looks like and of course you might

12:40 – David Tilly: want to make some changes along that development way to improve the insurance coverage and the pricing that might be available to you in general insurers are absolutely on board with working with clients on this. To Mike’s point, unfortunately, we are a data driven industry and until such time as we’ve got a plethora of data on there, there’s still going to be a little nervousness about deploying a huge amount of capacity on there just because we don’t have the numbers to plug into a modeling

13:07 – David Tilly: system.
Paul Lucas: I just want to ask you all about the warehouse and logistics space as well, if I can. Of course, e-commerce growth has driven demand in that space. So Mike, how is that changing the property risk landscape and indeed the underbriding approach that accompanies it?
Mike Ward: Yeah, sure. So, you know, we are seeing obviously the modern warehouses definitely have a larger footprint now. They’re storing more pieces of equipment, more stock, whatever they’re keeping there. And also, you know, a lot

13:35 – Mike Ward: of the modern warehouses do have solar panels on the top as well. So we are seeing insurers focusing more heavily on you know sprinkler protection how the stock or whatever is being there how is that being stored what is being stored and also and also the BI exposure uh you know supply chain dependencies and also the accumulation of the risk around the facility but again you know with tech technology improving we are seeing you know new technologies being implemented um you know real real time

14:07 – Mike Ward: monitoring uh of the building, you know, risk conditions such as, you know, sensors that track factors such as, you know, temperature, mechanical plant performance, when the fire protection systems are in place, you know, it literally generates thousands of data points per hour. So, you know, it’s that is key for property owners to identify potential issues before they actually develop into significant losses, which again is more repeated into insurers to, you know, so they know that the clients on the ball and they’re

14:36 – Mike Ward: doing again as much as they can to stop any claims happening.
Paul Lucas: And David, is there a concentration of risk here in in one area?
David Tilly: Absolutely. I mean maybe not in one area per se but certainly where you get a um a part of Europe, maybe a part of Asia where a lot of uh clients are building in the same general area. What you do start to see is the potential of a wide area event actually causing quite a huge amount of disruption to the to the industry and that can cover all sorts of

15:06 – David Tilly: uh industries like automation um you know last mile logistics on there and as you start to introduce automated robots and systems within the building obviously the fire risk starts to change and develop as that goes along. So I think again a lot of it comes down to engagement with brokers who your tenants going to be. Are you specifically fitting it out for a certain tenant in in which case do they have a history of how they fit that out? Do they have a profile of what they work to or are you literally building a shell and core and

15:37 – David Tilly: then letting your tenant build what however they like to do it fairly I guess un supervised which obviously brings in some different considerations in if you look purely from a concentration of risk perspective and potentially accumulation for one insurer that then comes down to data and potential restrictions in capacity which might be deployed in there and the fact that something like a hail storm across Europe, which we have certainly seen over the last couple of years and some flooding in there can have a much bigger

16:09 – David Tilly: effect than maybe they would have done maybe five, six years ago. But also then you’ve got the knock-on effect of these were maybe once flood planes or grasslands. These are now concrete industrial parks which in themselves have a secondary effect to other buildings and surrounding areas.
Paul Lucas: The Justin, you’re nodding along. It looks like you agree with David.
Justin Warents: Yeah, I would agree with those uh sentiments. Absolutely, Paul. Um, you know, I would say the best way of describing what’s

16:37 – Justin Warents: happening in logistics really is, as you’ve said, concentration of risk. Modern logistics warehouse can look relatively straightforward from the outside. Uh, but actually what’s sitting in in the inside of the building has changed enormously. It’s very complex. they these will there’ll be much greater automation as David alluded to ranging from robotics to sophisticated conveyor systems there’s high density storage and a lot of significant amount of IT infrastructure in in there as well

17:07 – Justin Warents: when you add together um roof mounted solar uh PV batteries EV charging then you you’ve got the potential for loss and it’s just not the cost of rebuilding these warehouses it’s the knock-on effects in the wider supply chain. Uh you know if you’ve got the head office um warehouse for a particular retailer um they’re reliant on that supply chain and if they have damaged that infrastructure that’s going to knock them back. So very loss of very expensive equipment business

17:39 – Justin Warents: interruption and of course the cost of rebuilding. So the thing to do here really is look at what the accumulation is um across several locations because as David had said these could be affected by the same uh perils you know flood storm uh in the environment. So it’s getting ahead of the curve, making sure that there’s good property data like we said before, accurate valuations, uh full uh detailed modeling of the asset and also you know business interaction uh analysis will go a

18:13 – Justin Warents: long way to differentiate one portfolio from the next to make that uh extremely competitive in the insurance market.
Paul Lucas: I just have one final question to throw at you all if I can and that’s just simply to ask what’s changed recently in how large and complex property losses are being handled specifically from a a claims perspective. Uh David, are you seeing any changes?
David Tilly: Well, I think the uh the introduction of technology to these claims responses certainly if I can capture the mood is

18:42 – David Tilly: is improving the speed of response uh to these losses. Um and that can be admittance of liability, understanding the um the cause of the loss and that can be the introduction of drones, um satellite imagery. Once upon a time, you know, just to get that data would have involved a battalion of soldiers getting down to the risk and with that comes time delays and everything else that that contributes towards. So I think in general technology is speeding up the ability to respond positively or negatively whatever way it needs to be

19:16 – David Tilly: from the claim. But we’re also now looking at other areas, not just, oh, the building’s had a fire. What are the knock- on effects of that? How long is it going to take to reinstate this building? We’ve got geopolitical influences across that across supply chains on there. And linking back to what we were saying earlier about retrofitting buildings for you know net zero when they are having losses are clients using this opportunity to potentially change the profile of the asset how they reinstate that. If they

19:44 – David Tilly: are maybe moving and pinching towards a greener building, then actually again does that have an impact on how long it’s going to take to reinstate that building, get the client back to where they were before the loss, but also is it going to have a cost impact and as I say supply chain issues about whether we can get those materials uh in a timely manner to deliver what the clients after.
Paul Lucas: Continuing the claims theme, Justin, are we seeing larger complex claims?
Justin Warents: Yes, Paul. Um we have the generally

20:14 – Justin Warents: the real estate market has is seeing larger losses um coming in you know across you know multiple asset classes. I would say the biggest change really in major property claims have become they’re much more forensic and they’re multi-disciplinary. Uh you know significant property losses today can evolve very quickly and they will involve a lot of a number of parties um working together. So you know David’s right from the perspective of you know using technology but this range

20:45 – Justin Warents: from this ranges from you know loss adjusters engineers um risk surveyors forensic accountants and potentially lawyers and coupled with the insurer and of course the broker there’s quite a you know a number of parties around the table discussing the claim and you know the optimum best outcome for this I think you know looking at mitigation um early on um claim preparedness, uh, modeling what a loss would look like on a portfolio cuz you’re not going to stress that test that, you know, at the

21:19 – Justin Warents: point of a loss, you’re just going to find either that your indemnity period for your business interruption was not long enough or, you know, unfortunately that your reinstatement value was short um, and you’ll have exposure there. So yeah, it’s extremely important for the broker to test all of this with the client. Making sure that major claims can be managed and looked at assessed well before an event happens I would say would be the would be the best thing. You know we buy insurance policy

21:48 – Justin Warents: for a reason and you know for it to respond to claims. So it’s important that that robustness um is there and will ultimately be the test of a quality insurance program.
Paul Lucas: Yeah. Uh Mike, from your perspective, do you think that the insurers, the loss adjusters, everybody across the kind of the value chain when it comes to claims, are they working together a little bit uh smoother now than they were before?
Mike Ward: 100%. Yeah. You know, we’re seeing insurers are actively bringing in

22:16 – Mike Ward: loss adjusters, forensic accountants, you know, even restoration specialists much earlier in in the claims process just to speed everything up. You know there’s definitely a stronger focus on you know business interruptions like supply chain disruption and obviously the challenge of getting the operation back up and running which is you know the most important but you know this has all been sped up again which been echoed here you know the use of drones remote inspections you know d the digital data

22:42 – Mike Ward: collection now is much more fast so you know it’s helping speed up the loss assessments and the resolution but again ultimately what we are hearing what we are seeing is you know obviously prior to use the priorities to make, you know, get claims settled as soon as possible, but also ensures that we want to work with businesses to be able to help them recover as quickly as possible and also obviously emerge more resilient for the future to make sure you know this sort of thing does happen

23:08 – Mike Ward: again that the claims costs remain as low as possible. Um, and you know, obviously the clients want to get back up and running as soon as possible. So, it should work in everyone’s favor really.
Paul Lucas: Great perspectives from everybody. Really interesting discussion. A huge thanks for your time. Remember, of course, that this group will be back together again one more time in 2026. But until then, keep it right here and Insurance Business TV.
 

Source

contact us